Overnight & Global
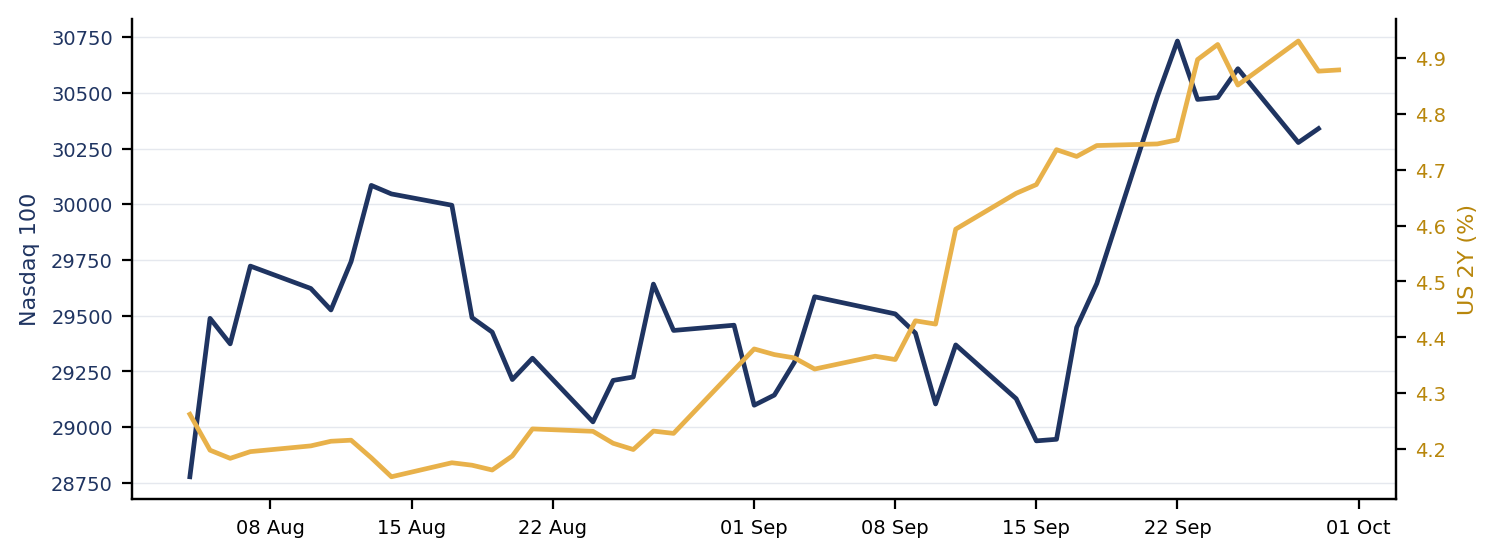
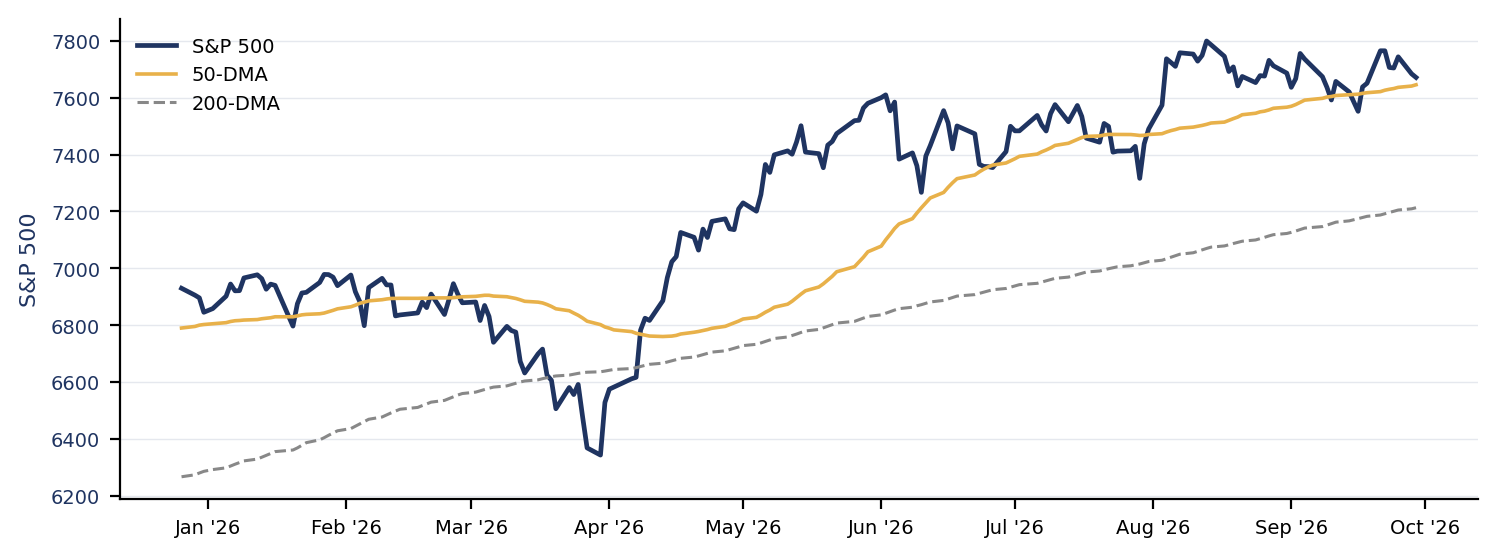
The long end made its highs on Monday, before the print that is supposed to decide it. The 30-year traded 5.613% intraday, the highest since June 2002, and closed 5.566% (+1.9bp); the 10-year printed 5.29%, the highest since 2007, and closed 5.236%, flat on the day and +27.5bp on the week. Take the week apart and it is real yield, not inflation compensation: the 10-year real is +25bp on the week to 2.888% while the breakeven is +2bp to 2.346%. That is a credibility move plus a term-premium move, not a de-anchoring, and it is why the Delphic Regime Radar's Monetary/Liquidity axis printed a new cycle high this morning. The front end went the other way: the 2-year fell 5.4bp after the New York Fed president said one further increase may be appropriate late this year, taking October hike odds from 71% to 49% with December the modal date. Equities absorbed the level through rotation until Monday, when they stopped: the S&P closed 7,670.84 (-0.17%), a point under its 20-day at 7,672; the Russell -0.35% and -2.8% on the week; the Nasdaq 100 +0.21%. VIX 16.04 did nothing; MOVE is 106.6, up 36% on the week. The stress is in rates, not equities, and one of them is early. Confidence fell to 81.9, the lowest since 2014, against a consensus of 89. Oil went the other way from the incident count: Brent settled $102.59 (-2.56%) on Kpler's September exports data as the SoH Monitor re-rated Hormuz crude throughput to 9.7 mb/d, with Yanbu loading again and four laden Qatari LNG carriers through in September, while a crude tanker was struck overnight and the formal US response to Tehran is due today through Doha. Then the print: ADP at 08:15 ET (consensus +70k) and at 08:30 ET August PCE (consensus core +0.3%, headline +0.4%), the annual revision back to 2021 and the third estimate of Q2 GDP. Nikkei +2.11% this morning.
Session Read
Four threads: a long end at 2002 highs on real yields alone; a print and a revision that decide whether the Fed is scored on a level or a path; a Strait whose physics improved while its diplomacy stayed open; and an Athens tape that reclaimed its 20-day as Wall Street lost its own.
The long end — the discount rate for everything, set by real yields and supply, not by inflation — The 30-year at 5.61% intraday is the highest since June 2002, and the decomposition is unambiguous: +25bp of real yield on the week against +2bp of breakeven. Three drivers run at once and none reverses on a soft print. The Fed: two voters said further adjustments are likely; the timing moved to December (October 49% from 71%), the direction did not. Supply: $2.42tn of net issuance over twelve months, net interest above $1.1tn. The carry channel: with the BoJ at 1.25% and the JGB 10-year at 3.08%, yen-funded selling of global duration does not read the PCE; we wrote on 23 September that the BoJ trigger did not transmit, and we now adopt the reading that it does. The S&P closed a point below its 20-day: the tactical box is back on, the stop on the adds a close below 7,645.
The print — our view, written before 08:30 ET so it can be scored — Delphic: core PCE +0.3% m/m (Cleveland nowcast 0.28), headline +0.4%, core about 3.4% y/y on the old basis. The Persistence Wedge stands: core PCE near 3.4 against core CPI 2.4, driven by healthcare, portfolio-management fees and financial services. The annual revision is the swing: the Street expects about 30bp off recent core as portfolio-management fees move to a new extrapolator and legal services and software to producer-price composites, back to 2021. A level shift to about 3.1% is still a point above target and above the Committee's own path to 2029; it does not satisfy the Chair's test that inflation move toward 2% clearly and at sufficient speed. Our off-ramp for the second hike is unchanged: two consecutive core prints at or below +0.15% m/m; a revised history does not qualify. The tape risk is asymmetric: positioning is short at 2002 highs, so a downward re-basing is the relief trigger for the 30-year and a 0.4% core the trigger for 5.65-5.75%. Path into the print: one more hike, December modal, no 2027 cut, first cut 2028, recession odds 15%. Read the spending line first: confidence at a 2014 low against intact spending is the Cost-Shock / Demand-Crack split, and today's outlays are its test.
Hormuz — the physics improved on monthly data, the diplomacy is unresolved, the market sold the front — The SoH Monitor holds Phase 2 (Fragile), velocity MIXED, base 55 / bear 25 / bull 20. The throughput scalar moves for the first time since 8 September, from 8.6 to 9.7 mb/d, on Kpler's preliminary September count (regional exports 16.3 mb/d, Saudi 5.4); it still fails the 12 mb/d gate at about 49% of baseline. Yanbu is loading again at roughly 2 mb/d, and four laden Qatari LNG carriers crossed in September against none in August, so the gas leg of the sustained-flow test is met; the crude and war-risk legs are not. The diplomacy is unresolved, not dead: indirect talks resumed on 28-29 September through Qatar, the formal US response is due today via Doha, and Washington now conditions a deal on the nuclear file. The violence has not stopped: a crude tanker struck overnight (damaged, not sunk), a Kuwaiti tanker on the 25th, 258 vessels stranded. Brent settled $102.59 (-2.56%) on the flow recovery, not the incident count. No Phase-1 trigger has fired. For the inflation path the shipping premium is the removable part; the damaged Qatari trains are the level that is not.
Europe, Athens and the trade truce — the rates channel is the euro story too — Athens reclaimed its 20-day on Monday (2,708, +1.6%) and held it on Tuesday at 2,709.91 (+0.08%) on turnover near EUR 467m with the banks +0.7%: Piraeus +1.7%, National +0.9%, Alpha +0.7%, PPC +1.4%. The ATHEX tactical's second tranche is back on, stop a daily close below the 50-day at 2,636. The Greek 10-year closed 4.482% (+2.1bp) against a Bund at 3.624%: the spread is stable, the level is not. Europe absorbed the US long end better than Wall Street (Euro Stoxx 50 +0.30%, DAX +0.10%), the banks the payer (SX7E -0.45%). The US-China lists landed on Monday: reciprocal cuts on $30bn each, 77 US categories and 1,619 Chinese items, no soybeans, truce extended to 10 January 2027; narrower than the summit rhetoric, a marginal positive for the goods-price leg. EM fell 0.46% with the dollar firmer (DXY 101.37).
Regime & Technical Radar
The Delphic Regime Radar's 30 Sep read: archetype unchanged, neutral / transitional, tightening-dominant late cycle, hardening into the print. Monetary/Liquidity at a NEW cycle high on a real-led long end; Growth down to +0.03 as the levered leg worsened; the new cross-asset scorecard shows the house long the 10-year strategically against a Street Model that is short it.
Archetype — NEUTRAL / TRANSITIONAL — tightening-dominant late cycle, NOT Goldilocks
Monetary / Liquidity — +0.74, NEW CYCLE HIGH — 30y 5.61 intraday (since 2002), 10y 5.29 (since 2007); real-led
Growth — +0.03 from +0.12 — copper momentum to zero, the levered leg (Russell) at its worst
Inflation — +0.48 — breakevens anchored (2.35 / 5y5y 2.32); the SURVEY channel de-anchored (UMich 4.6, CB 81.9)
Risk / Stress — +0.11, lifting — VIX 16.0 says no equity stress; MOVE 106.6 says the stress is in rates
the scorecard — UST 10y: house +2 strategic vs the Street Model -2 — a HORIZON SPLIT, not a contradiction
S&P 500 — 7,670.84 — a point BELOW the 20-day (7,672); 50-day 7,645 is the stop on the adds
UST 30y / 10y — 5.566% / 5.236% close; 5.613 / 5.29 highs — 24bp of the 40bp rates tripwire used
Athens GI — 2,709.91 — ABOVE the 20-day (2,687); second tranche back on; 50-day 2,636
Brent — $102.59 settle, 102.68 Asia — sold on flow recovery; CO12 carried at 80.27 (23 Sep)
The archetype does not move; the weight on one axis did, to a cycle high without the Fed's help. Monetary/Liquidity at +0.74 is a long end that priced the cycle on real yields, supply and the carry unwind; the breakeven leg failed to fire for a third week, so this is credibility, not de-anchoring. The uncomfortable pair is the survey channel against the market channel: households at 4.6% one-year expectations and confidence at a 2014 low, against a 5y5y at 2.32%; the Fed will be scored on which one it weights. Growth quietly deteriorated: +0.03 with copper momentum at zero and the Russell -2.8% on the week, the levered leg giving way first, the transmission we described in September arriving on schedule. The scorecard's one split is ours by design: the house is long the 10-year strategically on carry and the demand-crack hedge; the Street Model is short it on momentum; a difference between horizons is a stated position, and the tactical grade opens only when a ladder level prints.
Theme of the Day
THE FED WILL BE SCORED TODAY ON A LEVEL OR ON A PATH, AND THE REVISION DECIDES WHICH. THE LONG END HAS ALREADY VOTED THAT IT DOES NOT MATTER.
Two numbers land at 08:30 ET and only one is a data point. The August core print is the data point: consensus +0.3%, our call the same, a number that keeps December live and October a coin flip. The annual revision is the other thing: a re-measurement of the post-2021 inflation history, with portfolio-management fees re-based to a new extrapolator and legal services and software to producer-price composites, and the Street expecting about 30bp off recent core. If it prints, core PCE moves from about 3.4% to about 3.1% without a single price having changed, and the lunchtime argument will be that the Fed hiked into a mismeasured number. Our answer is that the Chair has told us his test, and it is not a level.
- The test is speed, not level. Inflation must move toward 2% clearly and at sufficient speed; 3.1% is a point above target and above the Committee's own path to 2029, and it is the same 3.1% the Persistence Wedge already attributes to administered and asset-linked prices. A revision narrows the wedge by construction; it does not touch the CPI, the wage tracker at 4.1%, PMI input prices at a 2022 high or household expectations at 4.6%.
- The tape is asymmetric. The 30-year set a 24-year high on Monday on real yields and supply, with positioning short and MOVE at 106. A downward re-basing is the headline a crowded short covers on: expect 15-25bp of relief in the long end, a re-pricing of the front-end path rather than of the term premium that set the high. A 0.4% core puts the 30-year at 5.65-5.75% by the afternoon.
- The policy consequence is symmetric. Neither outcome changes the direction of the next Fed move, both change its timing, and only the hot print changes the long end's level for more than a day.
- Read spending first, not the deflator. Confidence at a 2014 low against a 5% nowcast is the Cost-Shock / Demand-Crack split in one release; the day the spending line breaks is the day this regime changes.
Risks
- A downward revision read as vindication of the cuts trade, and a 25bp long-end rally into short positioning. We think it re-prices the front end, not the term premium, and would fade it in the 10-year; the first day belongs to the crowded side.
- A hot core on a 24-year high in the 30-year. 0.4% m/m puts the long end at 5.65-5.75% into an auction week with MOVE at 106 and 24bp of the 40bp rates tripwire used; Monday's close below the 20-day says equities have stopped paying through rotation.
- The survey channel is two prints deep: expectations at 4.6% and confidence at a 2014 low against an anchored 5y5y. If it reaches wages, the Persistence Wedge widens and no revision helps.
- Hormuz is a flow recovery with an incident rate. Base case a throttled corridor near 10 mb/d; the bear case is one laden hull sunk in-channel, a Phase-1 trigger and a $10-15 move in the front month.
The Call
THE CALL — score the Fed on the path, not the revised level; fade a revision rally in the front end, respect it in the long end; the spending line is the regime test, not the deflator.
This week's information is a level, not a print: the 30-year at 5.61% and the 10-year at 5.29%, set on real yields and supply before the data that was supposed to set them. On rates: one more hike, December modal, no cut in 2027, the first cut in 2028; nothing that prints today changes the direction. A revision that re-bases core PCE to 3.1% changes the Street's story, not the Chair's test, and we fade the front-end relief it produces; the long end is a different instrument, bought by the 10y/30y strategy by time and by level, never by chasing, so a 25bp relief on a revision is a day to do nothing. On equities: the S&P closed under its 20-day for the first time since the 21 September gate and leadership has narrowed to semis; stay with quality and self-funding balance sheets, trim duration not beta, and treat VIX at 16 as a tape that has not yet priced what MOVE at 106 has. On energy: the SoH re-rating to 9.7 mb/d and resumed Yanbu loadings are why Brent is $102 with a tanker struck overnight; the energy relief in the inflation path is banked once, the diesel crack remains the lagged core channel. On Greece: Athens reclaimed its 20-day on the banks as Wall Street lost its own; the second tactical tranche is back on with a defined stop, hedged through SX7E. The discipline for today: read the spending line before the deflator; it is the only divergence on this page that ends this regime.