Overnight & Global
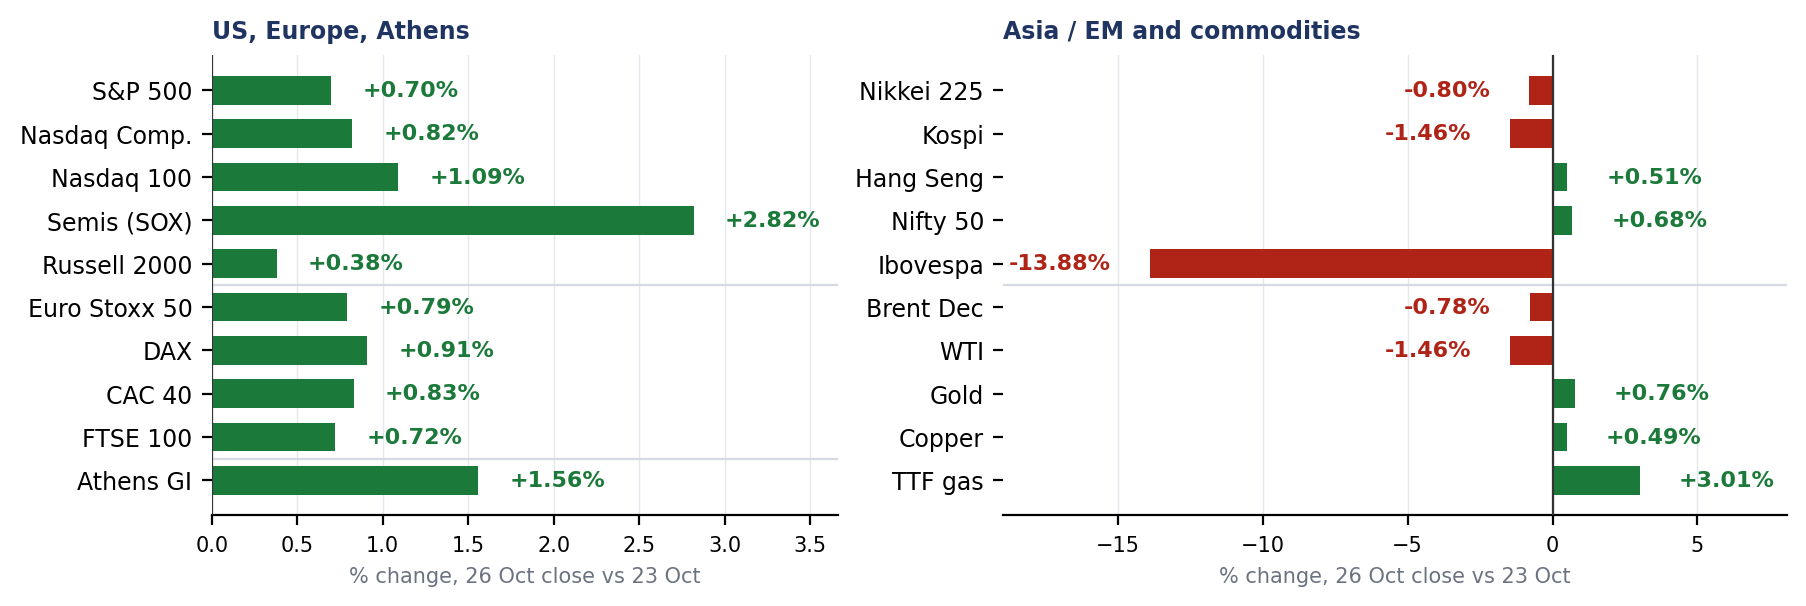
A Monday of relief with the Fed, Big Tech and oil all still ahead. The S&P gained 0.70% to 7,676.77 and the Nasdaq Composite 0.82% to 26,169.38, recovering the 22-23 October drop; semiconductors rose 2.8% (Philadelphia index 11,083) but are still 12.2% lower in October, and the Nasdaq 100 is -0.9% on the week while the Russell 2000 is +2.1%. VIX 18.39. The 10-year closed at 5.00% on the official par curve (4.98% on the market print), unchanged on the day and 15bp lower than 19 October after Thursday's 17bp fall, the biggest one-day drop in almost four years (CNBC); the 30-year is 5.31% and 2s30s 63bp. Europe added 0.8-0.9% (Euro Stoxx 50 6,116.23, DAX 25,410.84) and Athens +1.56% to 2,569.82, its first rise after two lower closes. The dollar firmed overnight (DXY 102.08, EUR/USD 1.1169, USD/JPY 157.71) and gold fell to $4,038.4, 2.9% lower on the week. Oil: the number to use is the December contract. Brent December settled $115.81 (-0.78%) after $116.72 on Friday, the highest close since 29 April, and is 5.7% higher on the week. The January contract that vendors now show as front-month, $109.84-109.93, is a different delivery month, not a fall; the gap between the two, and the $27.65 spread to the 12th contract ($88.16), is the shape of a market paying for prompt barrels. European gas followed: TTF €96.68/MWh, up 3.0% on the day, the highest since late 2022. Tactical read: the bounce is a relief, not a trend. The S&P sits below its 20-day (7,727) and 50-day (7,697) and above the 100-day (7,605); nothing is added into a negative tactical read, and nothing is sold in a market with the Fed, ECB and three hyperscaler prints inside four sessions. Own the 2-year, hold the 30-year receiver, keep the equity overweight, and do not buy gold on this dollar and this real yield (2.66% on 23 October).
Session Read
United States — chips rebound, the funding chain is the story. The rally was narrow in leadership and broad in participation. Technology, consumer discretionary and industrials led; communications, staples and health care, which had been at 52-week highs, gave a little back (Hammerstone Markets). Nvidia rose 2.4%, Tesla 5.2%, the Dow 0.28% to 52,361.58 and the Russell 2000 0.38%. The headlines were about who pays for AI. Anthropic filed publicly for a Nasdaq listing under the ticker ANT (press reports; TradingKey); Meta announced an underwritten equity sale of about $35bn ($22.5bn common, $12.5bn mandatory convertible preferred) with a further roughly $60bn at-the-market programme to follow, about $95bn in all, and fell 1.9%; SpaceX agreed about $40bn of GPU lease financing with Apollo-managed entities (TradingKey). Elon Musk's warning of "guppy-level death and consolidation" among neoclouds without non-AI revenue kept CoreWeave volatile (-5.5% intraday, closing +1.8%). Applying the house AI view: the earnings engine is confirmed and the avoid list is the debt-financed tail. A $95bn equity programme from a core hyperscaler is the opposite of a debt-financed tail; it moves the cost of the build onto shareholders, which is the funding-chain risk the house credit tripwires were built to watch (T1 primary accident armed, T2 spread derivative firing in the tail). Rates and the Fed: the 2-year auction ($69bn) cleared 0.3bp above the when-issued level, the 10-year is 5.00% and the Fed decision is Wednesday. Futures price a hold (CME FedWatch about 88% per press) and about an 80% chance of a December hike (Reuters). That is the house path, one more 25bp in December, with October at 25% in the house against a market about 88% for a hold.
Europe and Athens — Europe followed, Brazil broke, Athens bounced. Europe rose on the Wall Street lead and lower oil. The STOXX 600 closed +0.77% (640.66), Euro Stoxx 50 +0.79%, DAX +0.91%, CAC 40 +0.83%, FTSE 100 +0.72%; the euro-area rally was a relief on the 22-23 October bank drawdown rather than a re-rating, and the Euro Stoxx 50 is still 0.5% lower on the week. Brazil is the exogenous shock. Lula's re-election over Flávio Bolsonaro closed Brazil's exchange on a circuit breaker; the Ibovespa fell 13.88% to 176,608 and the real plunged (Reuters), with the MSCI emerging markets index down 0.96% and Asia-Pacific ex-Japan 0.15%. Spanish names with large Brazilian profits (Santander, Telefónica) fell sharply in Madrid, yet the IBEX closed +0.23%: the contagion is a stock-specific hit, not a euro-area bank signal. The house holds Brazil at neutral; one day of a 14% fall is a fiscal-risk re-pricing, not a basis to chase either way. Athens rose 1.56% to 2,569.82 after the 22-23 October drop of -4.3% over two sessions (2,643.62 to 2,530.46); S&P affirmed Greece at BBB, stable after the 23 October close (GreekReporter; ATHEX tactical). Greek bank closes for 26 October are not on our feed and none is quoted. The index sits 0.5% under its 100-day (2,582), with the 20-day (2,618) and 50-day (2,650) overhead: tactical negative, book held. Athens is closed on Wednesday 28 October for the national holiday and reopens into the ECB on Thursday; the systemic banks' Q3 prints start on 30 October. The ECB path holds: deposit rate 2.50%, 29 October live but not modal, 2.75% in December; markets price a hold on Thursday and a December move (Reuters/LSEG).
Asia / EM — chips lead the open; Korea hits the sidecar. Monday in Asia was soft; Tuesday opens on the AI bid. On 26 October the Nikkei fell 0.80% to 62,189.65 and the Kospi 1.46% to 5,469.47; the Hang Seng rose 0.51% and the Nifty 0.68%. This morning, intraday and not closes: the Nikkei is about +1.5% at 63,124, with AP reporting Advantest up 8.8%; the Kospi is about +3.3% at 5,650, SK Hynix +7% and Samsung +4.8%, with the Korea Exchange pausing programme buying on a sidecar (AP; press reports); the Hang Seng is -0.6% and the ASX 200 +0.5%. US index futures are flat to lower (S&P Dec -0.07%, Nasdaq 100 -0.37% against the 26 October settlements). The yen leg stays the cost in the house Japan overweight: USD/JPY 157.71 against a house year-end of 152. The Bank of Japan decides on Friday 30 October. The Kospi and Nikkei moves are a semiconductor-supply story; the house keeps Korea at a half-unit and Taiwan small because they are one AI-semis risk.
Theme of the Day
Capex is the test, and this week the market gets three answers and a bill. Microsoft and Alphabet report after the close on Wednesday, Amazon on Thursday (company schedules per press previews). The house carries 2027 hyperscaler capex at a ~$820bn base until these prints, with ~$1.2tn as the named upside case; no hyperscaler has guided 2027 yet. The funding side moved first. Meta's $35bn underwritten equity sale plus a roughly $60bn at-the-market programme (TradingKey; Investrade) puts a core hyperscaler's build on shareholders, not bondholders, and the stock fell 1.9%; SpaceX's $40bn GPU lease line and Anthropic's public listing filing add supply of AI paper in the same week. What the house reads: the earnings engine is intact (Micron 30 Sep, ASML 14 Oct) and the stress is in how the build is financed. Equity issuance by the core is the benign form of that stress; the tail (CoreWeave and the neocloud tier) is where credit breaks, and the T2 spread derivative is still firing there. Oil is the second input, and it can overrule the first. Applying the Forever War premium: December Brent at $115.81 against a house base of about $84 plus the Hormuz premium is the premium in plain view, and the calendar-2027 strip at $96.37 is above the ECB adverse-case line (~$92) that decides the ECB's terminal rate. Applying Trump Optionality: CNN reports US forces could launch a major operation within 96 hours of an order, with the order judged more likely after the 3 November midterms; Washington keeps both exits open. Hormuz as re-marked this morning (D241): Strait monitor Phase 2 held, base 37 / bear 48 / bull 15; five-way DEAL 15 / STRIKE 31 / SIEGE 37 / SALVO 9 / PROXY 8, resolution probability 24; strike risk about 12 before 3 November and about 19 after.
- Rates — overweight the 2-year, hold the 30-year receiver, no curve trade. The 2-year is 4.68%; the Fed path (one more 25bp in December, then 4.25% through 2027) is the house and the September FOMC median. 2s30s is 63bp; the steepener stopped out on 20 October.
- Equities — overweight, conviction 2; AI silicon and earnings compounders over bond proxies. Own NVDA, TSM, MU, GOOGL; avoid the debt-financed froth; underweight ORCL.
- Credit and inflation — HY underweight, IG neutral for carry, TIPS overweight. HY 338bp (23 Oct) is 9bp wider than 19 October; the breakeven at 2.34% still under-prices the Persistence Wedge and Brent December at $115.81.
- FX and gold — USD underweight strategically, spot against us. EUR/USD 1.1169 and USD/JPY 157.71 sit away from the house year-end (1.15 / 152); the re-score test (Sep-27 strip still 3+ hikes AND US-German 2-year gap at or above 178bp) is read at the 29 Oct ECB. Gold stays underweight: $4,038.4 on a real yield of 2.66%.
Regime & Technical Radar
The week tests the weeklies; the first day does not change them. The late-cycle read is refuted by a long end that keeps falling while earnings turn down. Today the long end is lower and the AI complex is the funding source, as on 22 October; nothing on 26 October contradicts it. New York needs 0.3% to return to neutral; Athens needs the 100-day back.
Synthesis
The information of the session is who funds the build. Anthropic's filing, Meta's $95bn equity plan and SpaceX's $40bn lease line moved the cost of AI from the credit market to the equity market in a single day, and the S&P still rose 0.70%. On rates: a 10-year at 5.00% and a 2-year at 4.68% price a Fed that hikes once more; the house path is one more 25bp in December, then 4.25% through 2027; October stays at 25%. On equities: overweight, conviction 2 the tactical read is negative until the 50-day (7,697) is regained, and the capex prints decide the next leg. On Europe: the ECB holds on Thursday on the house path (2.75% in December, 3.00% by March); the strip test reads on 30 October and, with the October average at $92.60 against the ~$92 line, the bear branch (3.25-3.50%) is the case to price, not the exception. France is the value call, timed to the 3 November PLF vote. On Greece: overweight, the sovereign affirmed BBB stable, a tactical negative on three lost lines; Athens reopens on Thursday into the ECB and the first bank print. On oil, FX and credit: Brent December at $115.81 with a calendar-2027 strip at $96.37 is the Forever War premium on display and the ECB's bear-branch trigger; Hormuz Phase 2 is held (base 37 / bear 48 / bull 15; DEAL 15 / STRIKE 31 / SIEGE 37 / SALVO 9 / PROXY 8; resolution probability 24) with the decision after 3 November. USD underweight with the re-score read at the 29 October ECB; HY underweight, IG for carry. Radar cross-check: late cycle, CONFIRMED. Recession odds 15%, growth 2.4% / 1.8% — held.